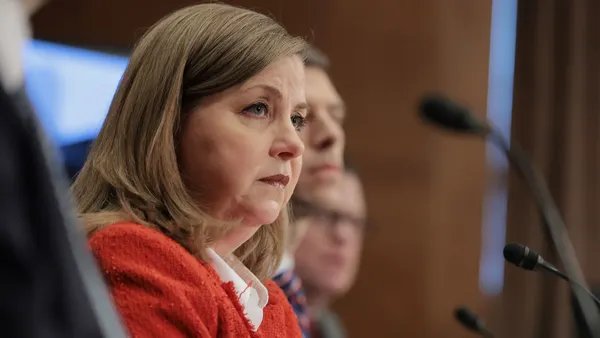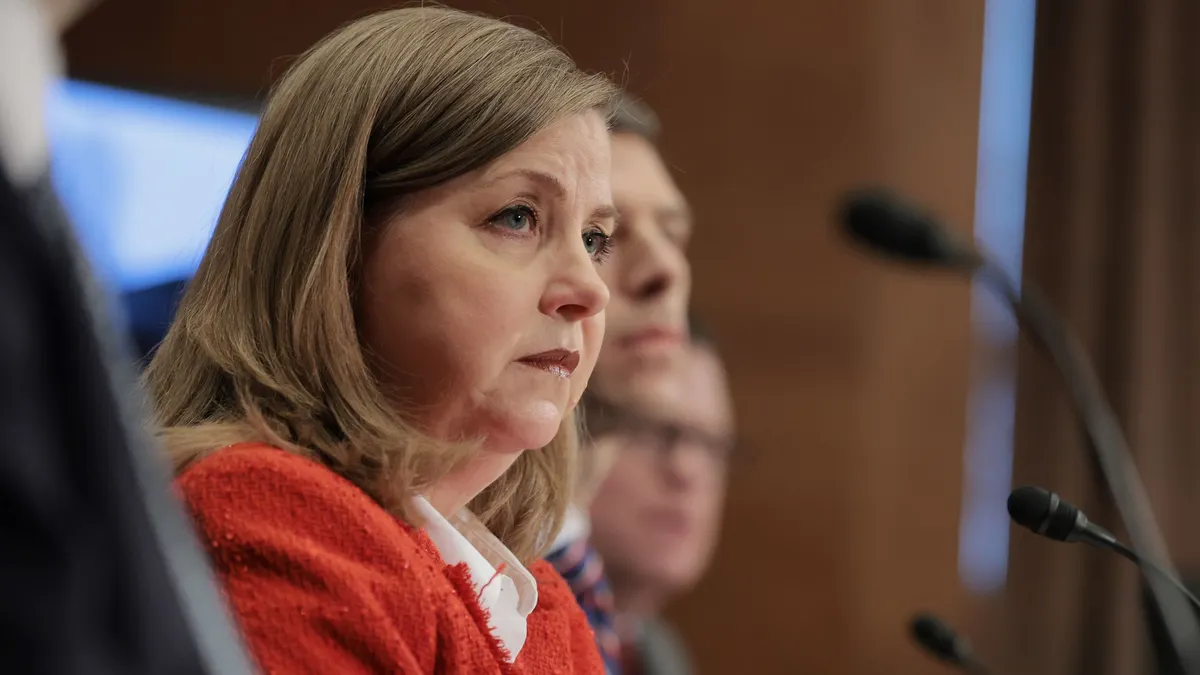
At a single luncheon in London on Friday, Michelle Bowman, the Federal Reserve’s vice chair for supervision, floated potential changes to bank stress tests, gave an overview of a new independent review of Silicon Valley Bank’s failure, and tied the two strands together. Here are three takeaways from her appearance.
1. First, a timeline.
Bowman said the Fed will consider final revisions to its stress testing framework in “coming weeks.” Additionally, she said she expects the central bank to finalize changes to risk-based capital requirements and the surcharge for global systemically important banks. (Incidentally, Bowman and the Fed were sued last week by an advocacy group over the capital-requirements changes, proposed in March.)
2. Considering more stress test changes.
Bowman spotlighted two public comments the Fed received over its stress-test rules. One suggested establishing a date on which banks’ balance sheets would be frozen before the Fed releases its annual stress-test scenarios. They’d be unfrozen shortly afterward.
Another comment recommends creating two global market shock scenarios in the test, with the larger loss used to calculate a bank’s stress capital buffer. Bowman said she will consider both comments in the upcoming final rule.
Bowman added that she wants the public to comment on another change for the 2027 test – namely, a revised model to evaluate noninterest income, the fee and trading revenue that banks earn from activities such as wealth management, investment banking and market making.
“In finalizing these reforms, we will finally close the book on an opaque and unnecessarily unpredictable framework,” Bowman said Friday.
Bowman also pushed for more communication between banks and the Fed.
“Scenario analysis is powerful on its own,” she said. “It becomes even more powerful when it is not a one-way exercise.”
For example, she said, large banks design and assess their own predicted performance amid severe scenarios.
“The Fed's stress tests should do more for our supervisors than calculate a single capital requirement,” Bowman said. “Fed stress tests should also identify a firm's vulnerability to various material financial and nonfinancial risks before those risks emerge. That information, in turn, will help inform how best to focus our supervisory attention across our large bank portfolios.”
She then turned her analysis on perhaps the most infamous bank failure of the 2020s.
“Had the Fed applied this type of analysis, supervisors could have measured the effect of a range of stressful scenarios on [Silicon Valley Bank’s] portfolios, exposures, and capital and liquidity positions,” Bowman said. “A plausible recession scenario, with rising interest rates and investment securities measured at fair value, would have shown the firm's capital falling below minimum required levels as early as the fourth quarter of 2021.”
As a sidebar, Bowman also delivered her assessment of the results of an independent review of SVB’s 2023 failure, which carried its own takeaways:
3. The Fed’s supervisory staff knew, or should have known, of SVB’s vulnerabilities as early as March 2022.
The central bank’s supervisory staff did not take prompt, decisive action to encourage or require SVB to reduce its interest rate risk or concentration of vulnerabilities, Bowman said.
Further, Bowman said the review cited a long-standing culture of risk aversion at the Fed, where staff believed it was safer to take no action than risk taking the wrong one. Additionally, supervisory staff were unsure who had the right to make the final call on which corrective action to take.
SVB’s collapse wasn’t the fault of one entity, Bowman said.
“It fundamentally shook public confidence in the effectiveness of bank supervision. That loss of confidence demands our response,” she said. “This review is not about assigning blame. Instead, it is about learning lessons from the past to avoid repeating them in the future.”